Mastering US Healthcare Enrollment: Your Essential 2026 Open Enrollment Guide
Navigating the complex landscape of US healthcare enrollment can often feel like deciphering a cryptic puzzle. With deadlines looming, plan options proliferating, and terms like ‘deductible,’ ‘copayment,’ and ‘out-of-pocket maximum’ swirling, it’s easy to feel overwhelmed. However, understanding and effectively managing your US healthcare enrollment is crucial for your financial well-being and access to necessary medical care. As Open Enrollment 2026 approaches, arming yourself with knowledge and a clear strategy is the best way to ensure you select a plan that truly meets your needs and budget.
This comprehensive guide is designed to demystify the US healthcare enrollment process. We’ll walk you through the critical steps, highlight key considerations, and provide actionable advice to help you make informed decisions. Whether you’re new to the system, experiencing a life change, or simply looking to optimize your current coverage, this article will serve as your indispensable companion for Open Enrollment 2026 and beyond. Prepare to take control of your healthcare future with confidence.
Anúncios
Understanding the Basics of US Healthcare Enrollment
Before diving into the specifics of Open Enrollment 2026, it’s vital to grasp the foundational elements of US healthcare enrollment. The American healthcare system is multifaceted, primarily comprising employer-sponsored insurance, government programs (like Medicare and Medicaid), and individual plans purchased through the Health Insurance Marketplace (also known as the exchange).
Anúncios
What is Open Enrollment?
Open Enrollment is a designated period each year when individuals and families can sign up for a new health insurance plan or make changes to their existing one. Outside of this period, you can only enroll or change plans if you experience a Qualifying Life Event (QLE), such as marriage, birth of a child, loss of other coverage, or moving to a new service area. For most people seeking coverage through the Health Insurance Marketplace, Open Enrollment typically runs from November 1 to December 15 for coverage starting January 1 of the following year. However, specific dates for Open Enrollment 2026 will be officially announced later, and it’s always wise to confirm these dates on Healthcare.gov or your state’s marketplace website.
Key Terms in US Healthcare Enrollment
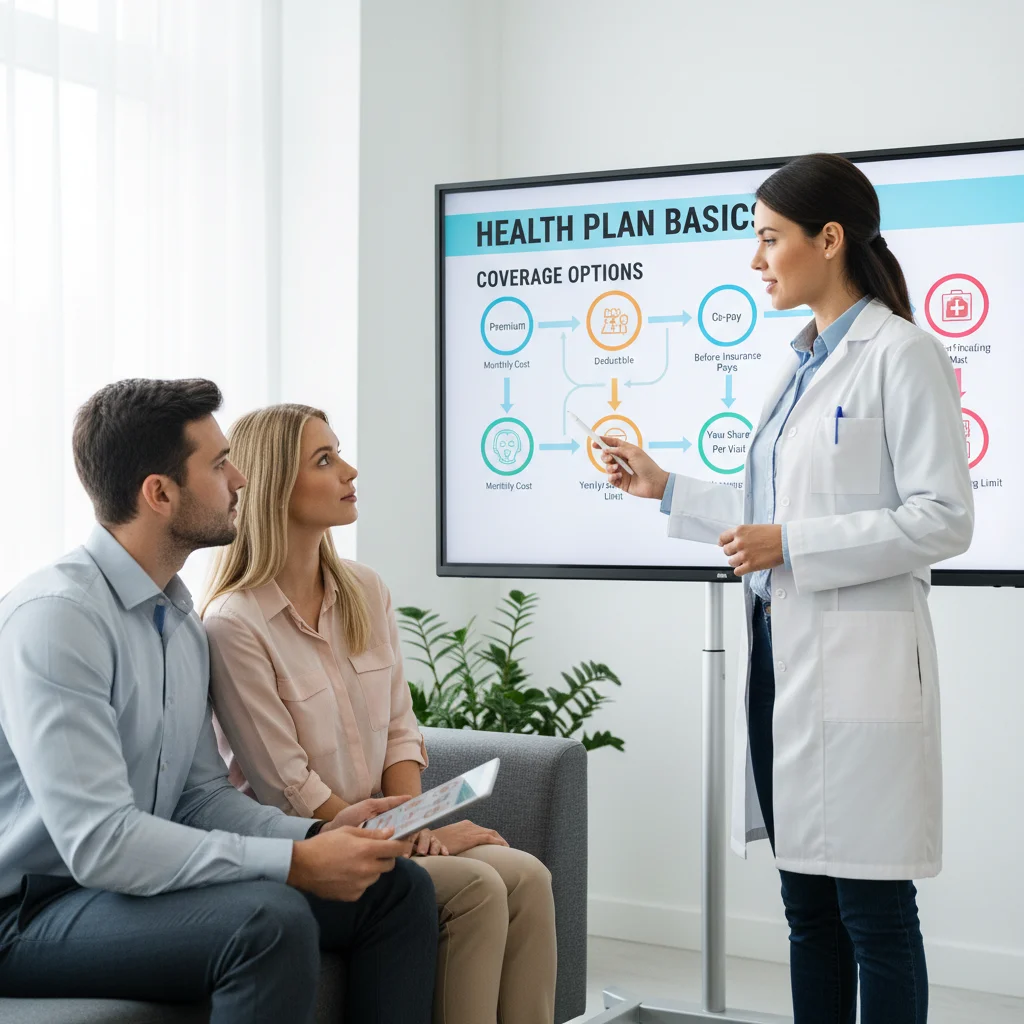
- Premium: The amount you pay monthly for your health insurance coverage.
- Deductible: The amount you must pay out-of-pocket for covered healthcare services before your insurance plan starts to pay.
- Copayment (Copay): A fixed amount you pay for a covered healthcare service after you’ve paid your deductible.
- Coinsurance: Your share of the cost of a covered healthcare service, calculated as a percentage (e.g., 20%) of the allowed amount for the service.
- Out-of-Pocket Maximum: The most you have to pay for covered services in a plan year. Once you reach this amount, your health plan pays 100% of the costs of covered benefits.
- Network: The group of doctors, hospitals, and other healthcare providers that your plan contracts with to provide services. Staying in-network generally results in lower costs.
- Formulary: A list of prescription drugs covered by your health insurance plan.
Step 1: Assess Your Healthcare Needs and Budget for Open Enrollment 2026
The first and most crucial step in successful US healthcare enrollment is a thorough self-assessment. What were your healthcare needs in the past year? What do you anticipate for the upcoming year? This introspection will guide your plan selection.
Reviewing Past Healthcare Utilization
Look back at your medical records for the past 12-24 months. Consider:
- Doctor Visits: How often did you see a primary care physician or specialists?
- Prescription Medications: What regular medications do you take? Check if they are covered on the plan’s formulary.
- Hospitalizations or Surgeries: Did you have any major medical events? While unpredictable, a history might indicate a need for robust coverage.
- Chronic Conditions: Do you manage any ongoing health issues that require frequent care or specific treatments?
- Preventive Care: Did you utilize annual check-ups, screenings, or vaccinations? Most plans cover these at no additional cost.
Anticipating Future Healthcare Needs
Think about any changes on the horizon:
- Family Planning: Are you planning to start a family or have another child? Maternity coverage is a significant factor.
- Upcoming Procedures: Do you anticipate needing surgery, therapy, or specialized treatments in the next year?
- Lifestyle Changes: Are you starting a new sport or activity that might increase your risk of injury?
- Aging Parents/Dependents: Are you responsible for dependents who might need more extensive care?
Setting a Realistic Budget
Your budget plays a significant role in your US healthcare enrollment decision. Consider not just the monthly premium, but also potential out-of-pocket costs.
- Monthly Premium: What can you comfortably afford each month?
- Deductible: Can you afford to pay a high deductible before your insurance kicks in? High-deductible plans often have lower premiums but higher initial costs.
- Copays/Coinsurance: How often do you expect to use services that require these payments?
- Out-of-Pocket Maximum: Do you have an emergency fund that could cover this worst-case scenario?
Remember, a lower premium doesn’t always mean a cheaper plan overall if you use a lot of medical services. Conversely, a higher premium might be a better value if it comes with a low deductible and comprehensive coverage for your anticipated needs.
Step 2: Exploring Your Options and Comparing Plans for US Healthcare Enrollment
Once you have a clear picture of your needs and budget, it’s time to explore the available health insurance plans. The primary avenues for US healthcare enrollment are employer-sponsored plans, the Health Insurance Marketplace, Medicare, and Medicaid.
Employer-Sponsored Health Plans
If you or your spouse work for a company that offers health benefits, this is often the most straightforward and cost-effective option. Employers typically subsidize a portion of the premiums, making them more affordable. During your company’s open enrollment period, review the plan options carefully. Pay attention to:
- Plan Types: HMO (Health Maintenance Organization), PPO (Preferred Provider Organization), EPO (Exclusive Provider Organization), POS (Point of Service). Each has different rules regarding network providers and referrals.
- Coverage Details: What are the deductibles, copays, coinsurance, and out-of-pocket maximums?
- Provider Network: Does your current doctor or preferred hospital participate in the plan’s network?
- Prescription Drug Coverage: Is your medication on the formulary, and what are the costs?
The Health Insurance Marketplace (Healthcare.gov or State Exchanges)
For individuals and families who don’t have access to affordable employer-sponsored coverage, or who are self-employed, the Health Insurance Marketplace is the go-to resource for US healthcare enrollment. During Open Enrollment 2026, you can compare plans from various private insurers. The Marketplace also offers financial assistance in the form of premium tax credits and cost-sharing reductions, which can significantly lower your costs based on your income.
Types of Plans on the Marketplace:
- Bronze Plans: Lowest monthly premium, highest deductible. Good for people who expect to use healthcare services infrequently.
- Silver Plans: Moderate monthly premium, moderate deductible. If you qualify for cost-sharing reductions, you must pick a Silver plan to get them.
- Gold Plans: High monthly premium, low deductible. Good for people who expect to use a lot of healthcare services.
- Platinum Plans: Highest monthly premium, lowest deductible. Pays the most for healthcare services.
- Catastrophic Plans: Available to people under 30 or with a hardship exemption. Very low premiums but very high deductibles, designed for emergencies.
When comparing plans on the Marketplace, use the comparison tools available. Filter by premium, deductible, out-of-pocket maximum, and even specific doctors or hospitals to narrow down your choices for US healthcare enrollment.
Medicare and Medicaid
- Medicare: Generally for individuals aged 65 or older, or those with certain disabilities or End-Stage Renal Disease. Medicare has its own specific enrollment periods. If you’re approaching 65, it’s crucial to understand Medicare Part A, B, C, and D and their enrollment windows to avoid penalties.
- Medicaid: Provides low-cost or free health coverage to low-income individuals and families. Eligibility rules vary by state, and enrollment is generally open year-round for those who qualify.
Step 3: Making Your Selection and Maximizing Your Benefits
Once you’ve diligently assessed your needs and explored the available plans, the final step in US healthcare enrollment is making your selection and understanding how to get the most out of your chosen plan.
Finalizing Your Plan Choice
Before you click ‘enroll,’ do one last check:
- Double-check Network Compatibility: Confirm that your preferred doctors, specialists, and hospitals are in-network. Call their offices directly to verify.
- Verify Prescription Coverage: Ensure all your necessary medications are on the plan’s formulary and understand their cost tiers.
- Understand the Summary of Benefits and Coverage (SBC): This standardized document provides an easy-to-understand overview of a plan’s benefits and coverage.
- Review Total Estimated Costs: Consider the premium plus potential out-of-pocket costs based on your anticipated healthcare use.
- Seek Assistance if Needed: Navigators, certified application counselors, or licensed insurance agents can provide free, unbiased assistance with US healthcare enrollment, especially when dealing with complex situations or subsidies.
Understanding and Using Your New Plan Effectively
Enrolling is just the beginning. To truly maximize your benefits and ensure a smooth healthcare journey, proactive engagement with your plan is key.
Key Actions After Enrollment:
- Receive and Review Your Welcome Packet: This will contain your insurance card, member ID, and detailed information about your plan.
- Set Up Your Online Account: Most insurers offer online portals where you can track claims, find in-network providers, and manage your benefits.
- Understand Your Preventive Care Benefits: Most plans cover a range of preventive services (annual physicals, screenings, immunizations) at no cost. Utilize these to maintain your health and catch potential issues early.
- Know When and How to Get Care: Understand the difference between emergency room visits, urgent care, and telehealth options. Knowing where to go for specific needs can save you time and money.
- Track Your Deductible and Out-of-Pocket Maximum: Keep an eye on how much you’ve paid towards these limits throughout the year. Your online portal should provide this information.
- Understand the Appeals Process: If a claim is denied, know your rights and the steps to appeal the decision.
Special Considerations for US Healthcare Enrollment
Qualifying Life Events (QLEs)
As mentioned, outside of Open Enrollment, you can typically only enroll in or change plans if you experience a QLE. These include:
- Marriage or divorce
- Birth or adoption of a child
- Loss of other health coverage (e.g., job loss, turning 26 and coming off a parent’s plan)
- Moving to a new area where your current plan isn’t available
- Significant change in income affecting subsidy eligibility
You usually have a 60-day window from the date of the QLE to enroll in a Special Enrollment Period (SEP). Don’t miss these deadlines!
Short-Term Health Insurance
While not considered comprehensive coverage under the Affordable Care Act (ACA), short-term health insurance plans can provide temporary coverage for unexpected medical needs. They generally have lower premiums but offer fewer benefits, do not cover pre-existing conditions, and do not include essential health benefits mandated by the ACA. They are typically used as a bridge between comprehensive plans, not a long-term solution for US healthcare enrollment.
Dental and Vision Coverage
Many health insurance plans do not include extensive dental or vision coverage, especially for adults. You may need to purchase separate stand-alone dental and vision plans. Children’s dental and vision coverage is considered an Essential Health Benefit under the ACA, so it’s often included or available as an add-on to Marketplace plans.
Health Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs)
These are tax-advantaged savings accounts that can be used for healthcare expenses. HSAs are available with high-deductible health plans (HDHPs) and offer triple tax advantages (tax-deductible contributions, tax-free growth, tax-free withdrawals for qualified medical expenses). FSAs are employer-sponsored and allow you to set aside pre-tax money for healthcare costs, though funds typically must be used within the plan year or a short grace period.
Common Pitfalls to Avoid During US Healthcare Enrollment
To ensure a smooth US healthcare enrollment experience, be aware of these common mistakes:
- Missing Deadlines: The most critical error is simply missing the Open Enrollment window or a Special Enrollment Period. Mark your calendar!
- Underestimating Healthcare Needs: Choosing a bare-bones plan to save on premiums when you anticipate significant medical needs can lead to much higher out-of-pocket costs.
- Overlooking Network Restrictions: Assuming your doctor is covered without verifying can result in unexpected out-of-network bills.
- Ignoring Financial Assistance: Many people are eligible for premium tax credits or cost-sharing reductions through the Marketplace but don’t apply, missing out on significant savings.
- Not Reviewing Prescription Coverage: Your medications are a major component of your healthcare costs. Always check the formulary.
- Failing to Understand Key Terms: A lack of understanding of deductibles, copays, and coinsurance can lead to costly surprises.
- Only Focusing on Premium: While important, the monthly premium is only one piece of the puzzle. Consider the total cost of care.
The Future of US Healthcare Enrollment and Open Enrollment 2026
The landscape of US healthcare enrollment is dynamic, subject to legislative changes and market shifts. As we look towards Open Enrollment 2026, it’s reasonable to expect continued efforts to expand access and affordability, potentially through enhanced subsidies or new plan offerings.
Stay informed by regularly checking official sources like Healthcare.gov, your state’s health insurance marketplace, and reputable news outlets for updates. Policy changes can impact eligibility for financial assistance, the types of plans available, and even the duration of the enrollment period. Being proactive and staying current with information will empower you to make the best decisions for your US healthcare enrollment.
Conclusion: Your Path to Confident US Healthcare Enrollment
Navigating US healthcare enrollment doesn’t have to be a source of stress. By following a structured approach – assessing your needs and budget, thoroughly exploring your options, and making an informed selection – you can confidently choose a health insurance plan that provides the coverage you need without breaking the bank. Open Enrollment 2026 is your opportunity to review, adjust, or initiate your health coverage journey.
Remember that healthcare is a personal journey, and the ‘best’ plan is always the one that best fits your individual or family circumstances. Take the time, do your research, and don’t hesitate to seek expert guidance. With this comprehensive guide, you are well-equipped to master your US healthcare enrollment and secure peace of mind for the year ahead.