Navigating 2026 Medicare Part D Changes: Your Essential Enrollment Guide
As we approach 2026, significant changes are on the horizon for Medicare Part D, the prescription drug benefit that millions of Americans rely on. These reforms are designed to make prescription drugs more affordable and improve the overall structure of the program. Understanding these Medicare Part D 2026 changes is not just beneficial; it’s essential for smart healthcare planning. This comprehensive guide will walk you through what to expect, how these changes might impact you, and the best strategies for enrolling in or adjusting your Part D plan.
The landscape of healthcare coverage is constantly evolving, and Medicare Part D is no exception. The reforms slated for 2026 stem primarily from the Inflation Reduction Act (IRA) of 2022, which introduced several key provisions aimed at lowering drug costs for beneficiaries. For many, these changes will translate into substantial savings and a clearer understanding of their out-of-pocket expenses. However, navigating these new rules requires careful attention and a proactive approach to ensure you select the plan that best meets your needs.
This article aims to be your definitive resource, breaking down complex legislative jargon into actionable insights. We’ll cover everything from the new out-of-pocket spending cap to changes in premium costs and the elimination of the 5% coinsurance in catastrophic coverage. By the end, you’ll be well-equipped to understand the implications of Medicare Part D 2026 and confidently make informed decisions about your prescription drug coverage.
Anúncios
Understanding the Core Medicare Part D 2026 Reforms
The Inflation Reduction Act of 2022 is the driving force behind the upcoming Medicare Part D 2026 changes. While some provisions of the IRA have already begun to roll out in 2023 and 2024, 2026 marks a pivotal year for the most impactful reforms. These changes are designed to provide greater financial protection and predictability for Medicare beneficiaries who rely on prescription medications.
The Out-of-Pocket Spending Cap: A Game Changer
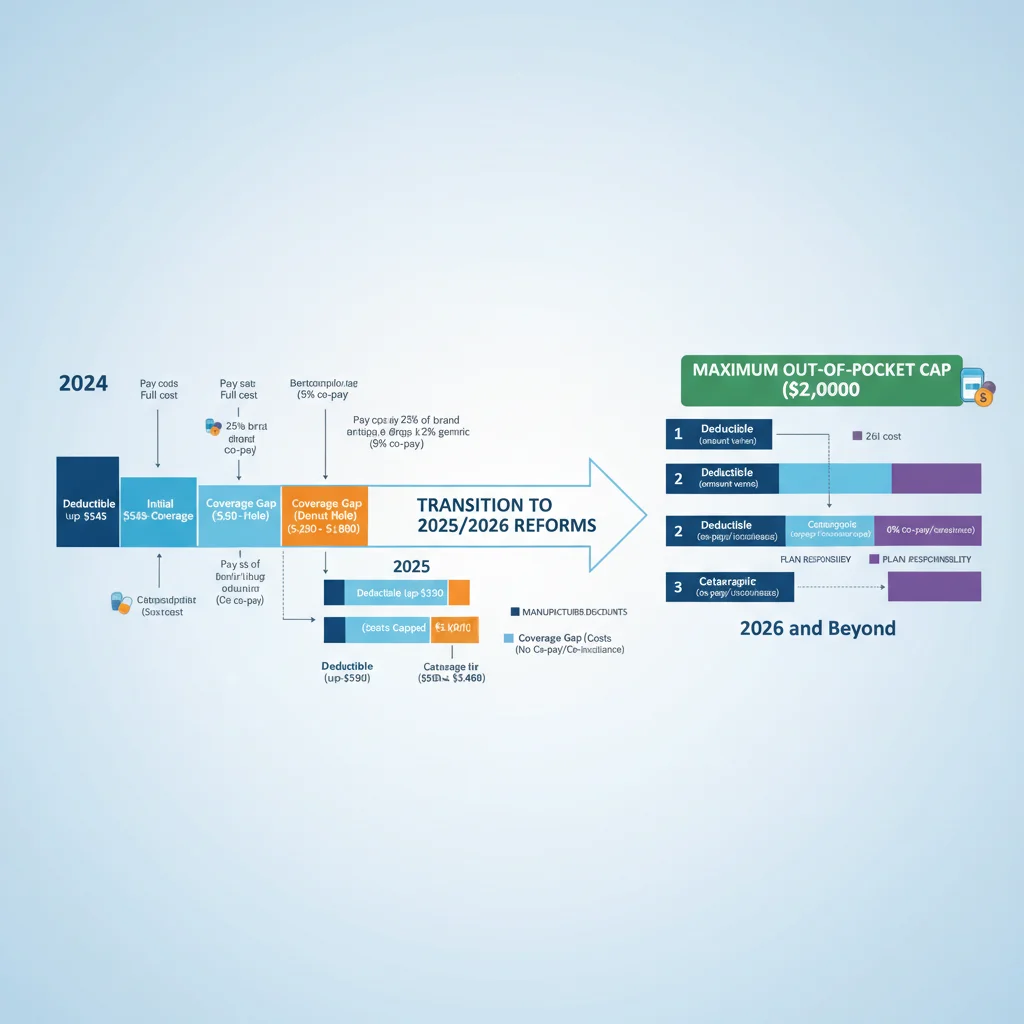
One of the most significant and anticipated changes in Medicare Part D 2026 is the establishment of an annual out-of-pocket spending cap. Starting in 2025, this cap will be set at $2,000, significantly reducing the financial burden for individuals with high prescription drug costs. Prior to this, while there were phases of coverage, there was no hard limit on how much a beneficiary might have to pay out of their own pocket in a given year. This cap means that once your out-of-pocket costs reach $2,000, you will not have to pay anything further for your covered prescription drugs for the remainder of the year.
This cap includes your deductible, your initial coverage phase costs, and what you pay in the coverage gap (often referred to as the ‘donut hole’). The impact of this change cannot be overstated, particularly for those managing chronic conditions requiring expensive medications. It transforms the financial risk associated with Part D, offering peace of mind and greater budget predictability.
Elimination of the 5% Coinsurance in Catastrophic Coverage
Another monumental change arriving with Medicare Part D 2026 is the elimination of the 5% coinsurance requirement in the catastrophic coverage phase. Currently, once beneficiaries reach the catastrophic phase, they are still responsible for 5% of the cost of their drugs, or a small copayment, whichever is greater. This 5% can still amount to thousands of dollars for individuals with very high drug costs.
Effective in 2025, once you reach the catastrophic phase, you will pay $0 for your covered Part D drugs. This means that after hitting the $2,000 out-of-pocket cap, your prescription drug costs drop to zero for the rest of the year. This provision, combined with the spending cap, creates a powerful safety net, ensuring that no Medicare beneficiary faces unlimited costs for essential medications.
Changes to the Coverage Gap (Donut Hole)
While the out-of-pocket cap effectively eliminates the financial sting of the coverage gap for beneficiaries, it’s worth understanding how the structure of this phase is also being adjusted. The IRA continues to reduce beneficiary responsibility in the coverage gap, with drug manufacturers and plans absorbing more of the costs. While beneficiaries will still technically enter the coverage gap before reaching the $2,000 out-of-pocket cap, the financial impact will be limited by this cap.
These structural changes within the coverage gap, combined with the out-of-pocket limit, aim to make the entire Part D experience more seamless and less financially daunting. The goal is to ensure that beneficiaries can access their necessary medications without fear of exorbitant, unpredictable costs.
How These Medicare Part D 2026 Changes Impact You
The reforms coming in Medicare Part D 2026 are designed to benefit a wide range of beneficiaries, but the impact will be most profoundly felt by specific groups. Understanding how these changes might specifically affect your situation is crucial for effective planning.
Beneficiaries with High Prescription Drug Costs
Individuals who currently spend thousands of dollars annually on prescription medications will experience the most significant relief. The $2,000 out-of-pocket cap means a definitive limit on their annual drug expenses, providing unprecedented financial protection. This includes those with chronic conditions like cancer, multiple sclerosis, or complex autoimmune diseases that often require very expensive specialty drugs. For these individuals, the Medicare Part D 2026 changes represent a lifeline, transforming their ability to afford necessary treatment.
Beneficiaries in the Coverage Gap (Donut Hole)
While the term ‘donut hole’ will still exist structurally, its financial impact on beneficiaries will be largely mitigated by the $2,000 out-of-pocket cap. Currently, many beneficiaries find themselves paying a substantial percentage of their drug costs in this phase. With the cap, once your combined spending reaches $2,000, you will pay nothing further, regardless of whether you are technically in the coverage gap or the catastrophic phase. This simplifies the experience and removes the financial cliff many faced.
Beneficiaries Receiving Low-Income Subsidies (LIS)
Individuals who qualify for Extra Help (Low-Income Subsidy) already receive significant assistance with their Part D costs. The 2026 changes, while primarily targeting those with higher out-of-pocket spending, will still offer some benefits. For instance, the expansion of full Extra Help benefits in 2024 to those earning up to 150% of the federal poverty level means more people will qualify for reduced premiums, deductibles, and copayments. While the $2,000 cap may not directly impact those with full LIS as much, the overall program enhancements contribute to greater affordability across the board.
All Part D Beneficiaries
Even if you don’t anticipate hitting the $2,000 out-of-pocket cap, the Medicare Part D 2026 changes foster a more stable and predictable environment for all. The increased financial responsibility of drug manufacturers and plans within the program’s structure could lead to more competitive plan offerings and potentially slower premium growth in the long term, although premiums are subject to various market forces. The overall goal is to create a more sustainable and equitable prescription drug benefit for everyone.
Preparing for Medicare Part D 2026: Your Enrollment Strategy
With these significant changes approaching, proactive planning is key. The annual Medicare Open Enrollment Period (October 15 – December 7) is your opportunity to review and change your Part D plan. Here’s how to prepare for Medicare Part D 2026:
1. Review Your Current Medications
Before you even look at plans, make a comprehensive list of all your prescription medications, including dosages and frequency. This is the most crucial step, as your plan choice should always be driven by your specific drug needs. Pay close attention to any changes in your prescriptions or new medications you might anticipate needing.
2. Understand the New Cost Structure
Familiarize yourself with the $2,000 out-of-pocket cap and the elimination of catastrophic phase coinsurance. While these are positive changes, understanding how they interact with deductibles and copayments in the initial coverage phase is important. Knowing your potential maximum cost can help you evaluate a plan’s overall value, not just its premium.
3. Utilize Medicare’s Plan Finder Tool
The official Medicare Plan Finder tool (medicare.gov/plan-compare) is an invaluable resource. During the Open Enrollment Period, this tool will be updated to reflect the Medicare Part D 2026 plan offerings and their associated costs. Input your medications, preferred pharmacy, and income information (if you believe you might qualify for Extra Help) to get personalized plan comparisons. The tool will calculate estimated annual costs for each plan, making it easier to compare.
4. Compare Premiums, Deductibles, and Formularies
While the $2,000 cap is a major benefit, don’t overlook the basics. Compare monthly premiums: a lower premium might mean a higher deductible, but with the cap, this might be a viable option for some. Most importantly, check each plan’s formulary (list of covered drugs) to ensure all your prescriptions are covered. Also, note any restrictions like prior authorization or step therapy for your medications.
5. Consider Your Pharmacy Network
Ensure your preferred pharmacy is in the plan’s network. Many plans offer preferred pharmacy networks that provide drugs at a lower cost. If you have a strong preference for a particular pharmacy, verify its inclusion and cost-sharing levels within the plans you are considering for Medicare Part D 2026.
6. Look Beyond the Premium: Total Annual Cost
Don’t just choose the plan with the lowest monthly premium. Use the Plan Finder tool to estimate your total annual costs, which include premiums, deductibles, and estimated out-of-pocket drug costs up to the cap. A slightly higher premium might lead to lower overall costs if it means lower copayments for your specific drugs.
7. Seek Personalized Guidance
If you find the options overwhelming, don’t hesitate to seek assistance. State Health Insurance Assistance Programs (SHIPs) offer free, unbiased counseling to Medicare beneficiaries. You can also consult with licensed insurance brokers who specialize in Medicare plans. They can help you navigate the Medicare Part D 2026 changes and find a plan tailored to your needs.
The Broader Impact of the IRA on Medicare Part D
Beyond the 2026 changes, it’s important to recognize that the Inflation Reduction Act has a broader, ongoing impact on Medicare Part D. These earlier and continuing reforms also contribute to the overall goal of making prescription drugs more affordable.
Insulin Cost Cap
Starting in 2023, the cost of insulin for Medicare beneficiaries was capped at $35 per month per covered insulin product, regardless of the deductible or coverage phase. This has provided immediate and significant relief for millions of individuals with diabetes. This cap remains in place for Medicare Part D 2026 and beyond, offering continued predictability for insulin users.
Vaccine Costs
Also starting in 2023, certain adult vaccines recommended by the Advisory Committee on Immunization Practices (ACIP), such as the shingles vaccine, became free for Medicare Part D beneficiaries, with no deductible or copayment. This encourages preventive care and removes financial barriers to important health protections.
Drug Price Negotiation
A longer-term provision of the IRA allows Medicare to negotiate the prices of certain high-cost prescription drugs directly with manufacturers. While the first negotiated prices take effect in 2026, the list of drugs subject to negotiation will expand in subsequent years. This landmark change is expected to drive down drug costs for Medicare and, by extension, for beneficiaries, contributing to the sustainability of the program and potentially influencing future Medicare Part D 2026 plan offerings and pricing.
Inflation Rebates
The IRA also requires drug manufacturers to pay rebates to Medicare if they raise prices faster than the rate of inflation. This provision aims to curb excessive price increases, providing another mechanism to control prescription drug costs within the Part D program.
These various components of the IRA work in concert to reshape the financial landscape of prescription drug coverage under Medicare. While the $2,000 out-of-pocket cap and catastrophic phase changes are the most direct and immediate benefits for Medicare Part D 2026, the broader reforms signal a shift towards greater affordability and control over drug costs for beneficiaries.
Tips for Optimizing Your Medicare Part D 2026 Plan Choice
Choosing the right Medicare Part D plan can feel complex, but with the right approach, you can optimize your coverage and minimize your costs. Here are some additional tips for Medicare Part D 2026:
- Annual Review is Non-Negotiable: Even if you were happy with your plan last year, drug formularies, premiums, and cost-sharing can change annually. Your personal medication needs might also evolve. Always review your options during Open Enrollment.
- Check for Preferred Pharmacies: Some plans offer lower copayments if you use a ‘preferred’ pharmacy. If you have a go-to pharmacy, check if it’s preferred by the plans you’re considering.
- Consider Mail-Order Options: Many plans offer lower costs for a 90-day supply of maintenance medications through mail-order pharmacies. This can be a convenient and cost-saving option for long-term prescriptions.
- Understand Generics vs. Brand Names: Generic drugs are typically much cheaper than brand-name drugs. Discuss generic alternatives with your doctor if cost is a concern. Part D plans usually cover generics at a lower cost-sharing tier.
- Explore Extra Help: If your income and resources are limited, you might qualify for Extra Help (Low-Income Subsidy) to assist with Part D premiums, deductibles, and copayments. Apply through the Social Security Administration if you think you might be eligible.
- Watch for Special Enrollment Periods: Certain life events, like moving to a new service area or losing other credible prescription drug coverage, may qualify you for a Special Enrollment Period outside of the annual Open Enrollment.
- Don’t Be Afraid to Switch: If a new plan offers better coverage for your medications at a lower cost, don’t hesitate to switch. The Open Enrollment Period is designed for this flexibility.
Common Questions About Medicare Part D 2026
As these significant changes approach, many beneficiaries have questions. Here are answers to some frequently asked questions:
Will my Part D premium go down in 2026?
While the overall goal of the IRA is to reduce costs, individual plan premiums are determined by various factors, including the specific plan’s benefit design, the drugs it covers, and the market. The out-of-pocket cap and other reforms might influence plans to adjust their premium structures, but it’s not guaranteed that all premiums will decrease. Some might even increase. This is why comparing plans annually is so important.
What if I don’t take many prescription drugs? Do these changes still matter to me?
Even if you currently don’t take many prescriptions, unexpected health events can occur. Having a Part D plan, even a basic one, protects you from potentially catastrophic drug costs if you suddenly need expensive medications. The $2,000 out-of-pocket cap provides a valuable safety net for everyone, regardless of current drug usage. Furthermore, the penalty for not enrolling in Part D when you’re first eligible (unless you have other credible coverage) can accumulate over time, making it more expensive to enroll later.
How do these changes affect Medicare Advantage plans with prescription drug coverage (MAPDs)?
Medicare Advantage plans that include prescription drug coverage (MAPDs) must also adhere to the Medicare Part D 2026 rules, including the $2,000 out-of-pocket cap and the elimination of catastrophic phase coinsurance. If you are enrolled in an MAPD, these changes will apply to your plan’s drug coverage as well. It’s crucial to review your MAPD’s Evidence of Coverage annually to understand any changes to its drug benefits.
When is the best time to start planning for Medicare Part D 2026?
The best time to start planning is now. While the official plan details for 2026 won’t be released until the fall of 2025, understanding the upcoming structural changes allows you to approach your next Open Enrollment Period with a clear strategy. Begin by reviewing your current medication list and understanding your past year’s drug costs. This will give you a solid foundation for comparing plans when the 2026 information becomes available.
Conclusion: Empowering Your Medicare Part D 2026 Decisions
The upcoming Medicare Part D 2026 changes represent a significant step forward in making prescription drugs more affordable and predictable for millions of Americans. The $2,000 out-of-pocket cap and the elimination of catastrophic phase coinsurance are landmark reforms that will offer substantial financial protection, particularly for those with high drug costs.
While these changes are overwhelmingly positive, they do require beneficiaries to be proactive and informed. Take the time to understand how these reforms will impact your specific situation, review your medication needs, and utilize the resources available to compare plans effectively. By doing so, you can ensure you are well-prepared for Medicare Part D 2026 and select a plan that provides the best possible coverage for your health and your budget.
Don’t wait until the last minute. Start your research, gather your information, and be ready to make informed choices during the next Open Enrollment Period. Your health and financial well-being depend on it. These reforms are an opportunity to gain greater control over your healthcare costs, and with the right preparation, you can fully leverage the benefits of the new Medicare Part D 2026 landscape.